
If your home in Scotland has been flooded in the past, you may be worried that nobody will want to buy it, or that the flood will follow you through every stage of the sale. It is a common concern, particularly in towns beside rivers, on the coast and in areas where heavy rain overwhelms the drains.
The short answer is yes, you can sell a house in Scotland that has been flooded before. You must disclose the flooding honestly, and buyers, lenders and insurers will want to understand what happened, what was repaired and how likely it is to happen again. With the right paperwork, many previously flooded homes sell on the open market, and selling to a cash buyer is another option if insurance or mortgage questions become a stumbling block.
Key points at a glance
- Selling is possible: a flood history affects price and the pool of buyers, but it does not stop a sale.
- Disclosure is required: the Home Report property questionnaire asks about flood damage during your ownership and any outstanding insurance claim.
- Buyers will check the risk: SEPA flood maps and environmental searches show whether the area is at risk from rivers, the sea or surface water.
- Insurance is the big question: the Flood Re scheme helps many homes built before 1 January 2009 get affordable flood cover.
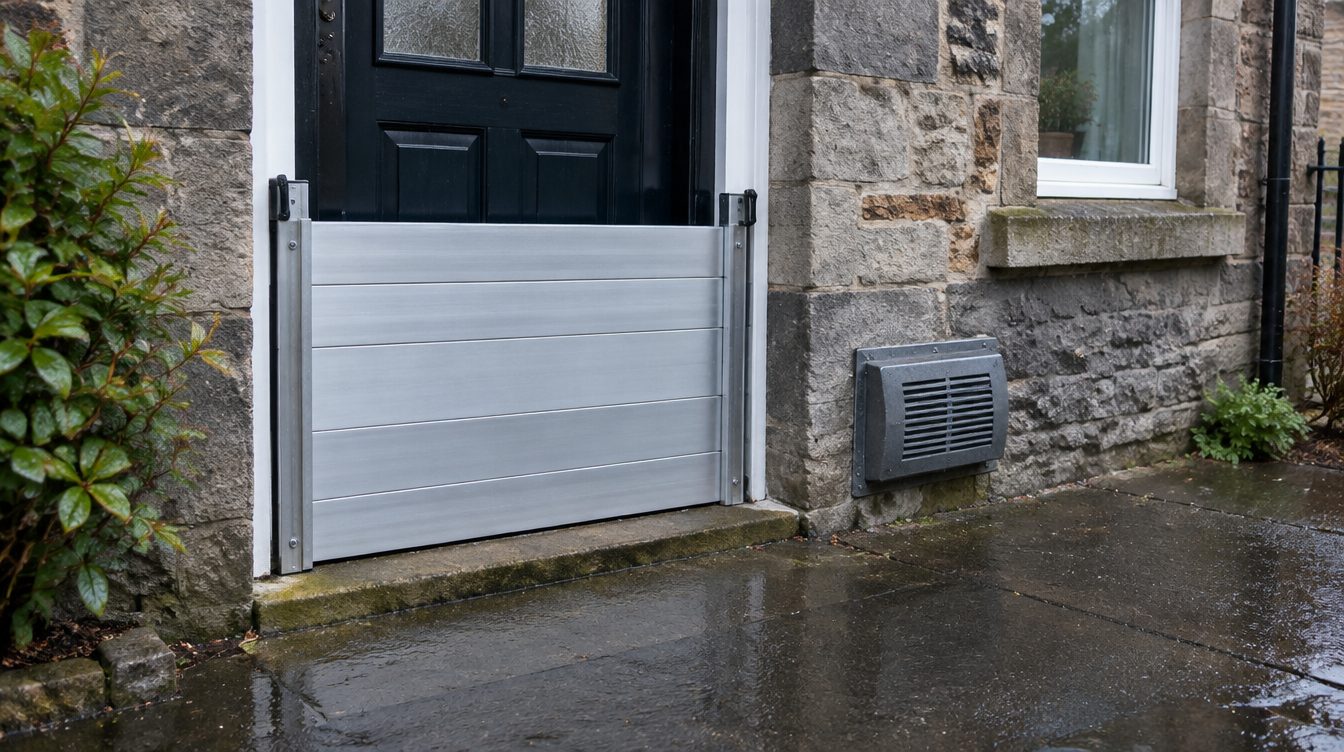
- Resilience measures help: flood doors, barriers and other property flood resilience measures can reassure buyers and insurers.
- Evidence matters: repair invoices, drying records and guarantees make a previously flooded home far easier to sell.
Can you sell a house in Scotland that has flooded before?
Yes. Plenty of homes in Scotland have been affected by flooding at some point, and they continue to change hands. The Scottish Government’s 2019 Living with Flooding action plan estimated that around 284,000 homes and premises in Scotland are at risk of flooding, so buyers, solicitors and lenders are used to dealing with the issue.
What changes is how carefully the sale has to be handled. A one off flood many years ago, caused by a burst pipe or a blocked drain that has since been fixed, will worry buyers far less than a home on a flood plain that floods every few winters. The more you can show about the cause, the repairs and the current risk, the better your chances of a smooth sale.
What counts as flooding?
- River flooding: water from a river or burn overtopping its banks.
- Coastal flooding: sea water driven inland by high tides and storms.
- Surface water flooding: heavy rain that cannot drain away quickly enough, often in towns and cities.
- Groundwater flooding: rising water underground, which tends to affect basements and low lying floors.
- Sewer or drain flooding: drains backing up and water entering the property.
Escape of water from inside the house, such as a burst pipe, is usually treated separately by insurers, but it should still be mentioned if it caused significant damage.
Do I have to tell buyers about past flooding?
Yes. The property questionnaire that forms part of the Scottish Home Report asks whether there has been any storm, flood, fire or other structural damage to the property while you have owned it and, if so, whether the damage is the subject of any outstanding insurance claim. It also asks about specialist work, such as damp treatment, and any guarantees.
The questionnaire focuses on your own period of ownership, but that does not mean you can stay silent about flooding you know happened before you bought. If the buyer’s solicitor asks, you must answer truthfully, and giving a misleading answer could leave you facing a claim after the sale under Scots law. Our guide on what Scottish sellers must disclose explains the wider principles.
Some online guidance refers to the TA6 form and English legislation. Those apply to sales in England and Wales. In Scotland, disclosure runs through the Home Report, your solicitor’s enquiries and the missives, so speak to your own solicitor about exactly what to say.
How will buyers check the flood risk?
Even if you are completely open, buyers and their advisers will carry out their own checks. In Scotland the main public source is SEPA, the Scottish Environment Protection Agency, which publishes flood maps showing areas at risk from rivers, the sea and surface water. SEPA is clear that its maps do not show the risk to individual properties, but they do show whether the area is affected.
- SEPA flood maps: show whether the surrounding area is at risk of river, coastal or surface water flooding.
- Environmental searches: many buyers’ solicitors order a report that summarises flood, ground and contamination risks for the address.
- Floodline: SEPA’s free flood warning service. If your home is in a warning area, buyers may ask whether you are registered.
- Local knowledge: buyers increasingly look at local news, council flood schemes and community groups, so past events are rarely hidden for long.
It is worth checking the SEPA maps yourself before you market the house, so you are not caught off guard by questions. If the maps show low risk and your flood was caused by something specific that has been fixed, such as a blocked culvert or a failed drain, say so and keep the evidence ready.
How does a flood history affect the Home Report and valuation?
The surveyor who prepares the single survey will look for visible signs of past water damage, such as tide marks, damp readings, damaged plaster or floor timbers, and may note if the property is in an area known to flood. Any defects are rated from category 1 (no immediate action needed) to category 3 (urgent repairs or replacement are needed now), and the valuation reflects the property’s condition.
A well repaired home with a single historic flood may see little effect on value. A property with ongoing damp, incomplete repairs or a pattern of repeated flooding is likely to be valued lower and attract fewer offers. If your report has already flagged problems, our guide on what to do when a Home Report highlights major problems explains your options, and our article on selling a house with damp or structural issues covers the knock on effects of water damage.
Will the buyer be able to get insurance?
For many buyers, this is the deciding question. Mortgage lenders usually require buildings insurance from the date of entry, and a home with a flood history can be expensive or difficult to insure on the open market. This is where Flood Re comes in.
Flood Re is a joint initiative between the UK Government and insurers that helps households in flood risk areas get affordable home insurance. Homeowners do not apply to Flood Re directly. Instead, participating insurers can pass the flood part of an eligible policy to the scheme, which keeps the premium more affordable. The scheme is designed to run until 2039.
Is the property eligible for Flood Re?
According to Flood Re’s own eligibility criteria, a property must meet all of the following conditions:
| Flood Re requirement | What it means in practice |
|---|---|
| Built before 1 January 2009 | Newer homes are excluded, as they should have been built with flood risk in mind. A pre 2009 home that was demolished and rebuilt still qualifies. |
| Domestic Council Tax band A to H | The property must be a home, not business premises paying non domestic rates. |
| Private, residential use | Homes, holiday homes and some farmhouses can qualify; commercial portfolios cannot. |
| Insured by an individual | The policy must be in the name of one or more individuals (or a personal representative), not a company. |
| Lived in by the policyholder or family, or unoccupied | Tenanted buy-to-let homes usually fall outside the scheme unless they meet all the criteria. |
| A single home or a building of up to three homes | Large blocks of flats are excluded for buildings cover, although individual contents cover may still qualify. |
Flood Re also supports a Build Back Better option, through which participating insurers can contribute up to £10,000 towards property flood resilience measures when repairing a home after a flood claim, on top of the normal repairs. Each insurer sets its own limit, so check the policy wording.
Good to know: if you are selling a home built after 2009, or one that does not meet the Flood Re criteria, ask your current insurer whether they would offer cover to a new owner. Being able to tell buyers that cover is available, and roughly what it costs, can save a sale. If your flood insurance claim is still open, our guide on selling with an unresolved insurance claim explains how open claims are handled.
Will mortgage lenders lend on a previously flooded home?
Many lenders will, provided the property has been properly repaired, the valuer is comfortable with its condition and the buyer can arrange buildings insurance. Lenders are more cautious where there is evidence of repeated flooding, unrepaired damage or no realistic insurance option. A cautious lender can cause a sale to stall late on, as explained in our guide to what happens if a buyer’s mortgage is declined.
Who is responsible for protecting a home from flooding in Scotland?
In Scotland, the responsibility for protecting a property from flooding rests with its owner. The Scottish Government, SEPA, local councils and Scottish Water work together under the Flood Risk Management (Scotland) Act 2009 to manage flood risk at national and local level, through Flood Risk Management Strategies and Local Flood Risk Management Plans. Some communities benefit from formal flood protection schemes, but many homes are not covered by one, and even protected areas can still flood.
For a seller, this matters in two ways. A council flood scheme built since your flood can genuinely reduce the risk, so mention it. And any steps you have taken yourself to protect the house are a selling point worth documenting.
Which flood resilience measures reassure buyers?
Property flood resilience (PFR) measures fall into two groups: resistance measures that help keep water out, and recovery measures that reduce the damage and speed up the clean up if water does get in. SEPA notes that insurers may take PFR measures into account, and that some insurers expect flood products to be certified to an industry standard.
| Measure | Type | How it helps |
|---|---|---|
| Flood doors or removable door barriers | Resistance | Stop or slow water entering through doorways |
| Air brick covers and sealed service entry points | Resistance | Close off gaps that let water into walls and under floors |
| Non return valves on drains | Resistance | Prevent sewage and drain water backing up into the house |
| Raised sockets, boilers and meters | Recovery | Keep essential services working and reduce repair costs |
| Tiled or solid floors and water resistant plaster | Recovery | Allow rooms to be cleaned and dried rather than stripped out |
| Sump and pump | Recovery | Removes water from under floors or basements more quickly |
If your home is listed or in a conservation area, check with the council before fitting external barriers or replacement doors, as consent may be needed. Our guide to selling a listed property or one in a conservation area explains how those controls work. The Scottish Flood Forum, a charity, also offers independent advice to people affected by flooding.
What paperwork should I gather before selling?
- A short written account: when the flooding happened, the source of the water, how far it reached and how long it lasted.
- Insurance records: claim references, confirmation the claim is closed, and details of your current cover and premium.
- Repair evidence: invoices, drying out records and photographs of the work.
- Guarantees: for damp proofing, timber treatment or other specialist work, which the property questionnaire asks about.
- Flood resilience details: product certificates and installation records for doors, barriers or valves.
- Any flood risk report: if you commissioned one, along with details of any council flood scheme nearby.
Gathering this before you market the house makes it easier for your solicitor to answer enquiries quickly. Our checklist of documents you need to sell a house in Scotland covers the rest of the paperwork.
Should I repair flood damage before selling?
If repairs are covered by an insurance claim, it usually makes sense to let the claim run its course so the work is done properly and documented. If you are paying yourself, weigh the cost against the likely effect on the price. Our guide on whether you need to fix repairs before selling can help you decide, and what can reduce the value of a house in Scotland explains how buyers price in defects.
Flooding is not the only kind of damage that worries buyers. If your home has also suffered fire damage, read our guide on selling a fire damaged house in Scotland. If you live in a flat and the flood affected common parts of the building, our guide on selling a flat with a notice of potential liability for costs explains how shared repair bills are handled.
Is selling to a cash buyer a good option after a flood?
For some sellers, it is. If buyers keep withdrawing once they learn about the flood, or a lender or insurer becomes a sticking point, a buyer who does not need a mortgage removes much of that uncertainty. Our comparison of selling to a cash buyer or through an estate agent sets out the pros and cons.
The trade off is price: a cash buyer takes on the flood risk and any remaining work, so their offer will usually sit below full open market value. Our honest explanation of why cash buyers usually pay less explains how those offers are worked out.
At Sell My House Fast in Scotland, we buy houses for cash in their current condition, including homes that have been flooded. We will look at the paperwork you have, explain how we have arrived at our offer, and let you choose a date of entry that suits you. There are no viewings, no chain and no obligation. If you accept, our guide on what happens after a cash offer is accepted explains the next steps.
Frequently asked questions
Do I have to disclose a flood that happened before I owned the house?
The property questionnaire asks about flood damage while you have owned the property. If you know about earlier flooding and the buyer’s solicitor asks, you must answer honestly. Your solicitor can advise you on what to say.
Does Flood Re cover homes in Scotland?
Yes. Flood Re covers eligible homes across the UK, including Scotland. The home must have been built before 1 January 2009, be in Council Tax band A to H, be used for private residential purposes and meet the other eligibility criteria.
Can I check whether my home is in a flood risk area?
Yes. SEPA publishes flood maps showing areas at risk from river, coastal and surface water flooding. The maps do not show the risk to individual properties, but they give a good picture of the risk in your area.
Will a flood history always reduce the price?
Not always. A single historic flood with documented repairs, available insurance and resilience measures in place may have a modest effect. Repeated flooding, unrepaired damage or difficulty insuring the property will usually have a larger impact.
Can I sell while a flood insurance claim is still open?
Yes, but you must disclose the open claim, and many mortgage lenders will want repairs finished before they lend. Some sellers wait for the claim to finish, while others sell to a buyer who does not need a mortgage.
Want a straightforward sale after a flood?
If a flood history is making your sale harder, we can make a no obligation cash offer on your home as it is, with no viewings, no chain and a date of entry that suits you.
